THE SIGNAL IN ONE SENTENCE
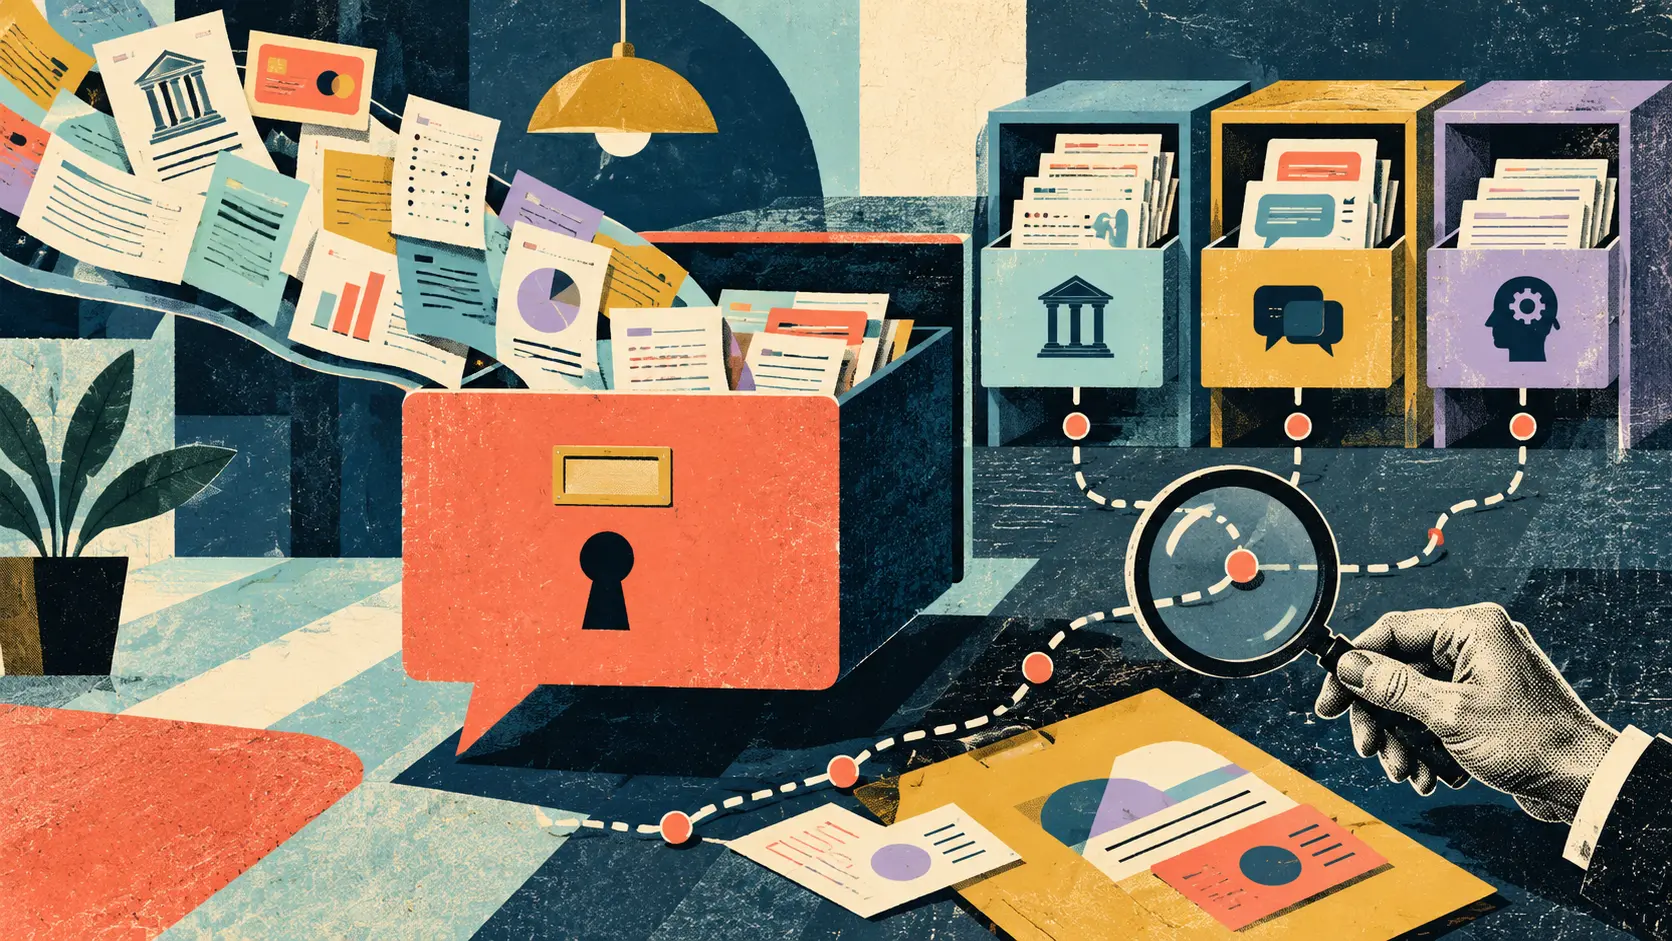
OpenAI has widened access to Finances in ChatGPT. The product is now rolling out to Free and Go users in the United States on the web, iOS and Android. Plus and Pro users already had access. Eligible users can connect financial accounts through Plaid, connect credit report data through Experian, inspect a dashboard and ask questions grounded in that data. The practical pitch is easy to understand. Instead of exporting transactions into a spreadsheet and trying to remember which streaming service quietly raised its price, you can ask where your money went, which bills are coming, how your portfolio is allocated or whether you are staying inside a grocery budget. ChatGPT can also keep financial memories. These are details you tell it about your financial life, such as a savings goal, a family loan, a shared rent arrangement or the amount you want to keep in checking. The system can use those details in later finance conversations. That is the feature worth watching. The plain signal is not simply that a chatbot can read a bank feed. Budgeting apps have done that for years. The meaningful shift is that connected records, conversational reasoning and durable personal context now sit in one general-purpose assistant available on free plans. That can be genuinely useful. It also means the data map matters more than the friendly answer. There are at least three different drawers in this cabinet. The first drawer is connected source data. Plaid can supply balances, transactions and other supported account fields. Experian can supply credit report data and a VantageScore 3.0 score. OpenAI says these are separate connections and people may use either or both. The second drawer is conversation history. If you ask why your electric bill rose and ChatGPT answers using connected data, the question and answer can remain in the conversation after you disconnect the financial source. The third drawer is financial memory. A fact such as I want to keep $2,000 in checking can be saved separately so future finance conversations have more context. OpenAI provides controls for each area, but the controls are not one giant erase button. The company says disconnecting Finances removes connected financial data from ChatGPT. Removing a Plaid connection causes synced account data to be deleted from OpenAI's systems within 30 days, and data associated with that ChatGPT connection is deleted from Plaid within 30 days under Plaid's policies. Disconnecting a source does not delete information already present in conversation history. Those conversations must be deleted separately. Financial memories can be viewed or deleted from the Finances page. Temporary chats do not access connected financial accounts, use memories or create new memories. None of this is hidden in the documentation. The problem is that people routinely interpret disconnect as forget everything. For a weather app, that misunderstanding is annoying. For a system holding mortgage context, account balances, debt questions and credit factors, it is a design problem. The cleanest version of Finances would give every answer a small data receipt. Which accounts contributed? When did each source last sync? Did the answer use Experian data, Plaid data, a financial memory, something typed into this conversation or the model's general knowledge? If a number conflicts with the bank's own app, which transaction categories or missing fields caused the difference? OpenAI says connected-data answers may cite the relevant source data, and the dashboard shows connection status and last sync time. That is a good start. The wording matters because source citation is described as something the system may do, not an iron rule attached to every material financial claim. Freshness is not a small detail. Financial institutions do not all provide the same history or fields through Plaid. One account may expose a balance but not complete transactions, holdings, loan details, annual percentage rates or due dates. Syncing can take minutes and, rarely, hours. A credit report reflects what lenders have reported to Experian, not live activity. OpenAI says credit widgets use the latest Experian report and a recent payment may not appear until the lender reports it and the file updates. Then there is categorization. A transfer can look like spending. A credit card payment can be counted beside the purchase it paid for. A pending transaction can duplicate a posted one. A reimbursement can make a category look worse before it looks better. OpenAI explicitly warns that spending breakdowns may be inaccurate and that AI can make mistakes. That is refreshingly direct. It also tells us how the tool should be used. Finances is best treated as a conversational workbench, not a ledger of record. Use it to locate patterns, prepare questions and test scenarios. Ask it to list the transactions behind a conclusion. Check a bank, brokerage, bill or credit report before acting on a surprising answer. Keep the authoritative number in the authoritative source. The product's action boundary is also clear. ChatGPT cannot move money, pay bills, change account settings, make trades, alter retirement contributions, open or close accounts or file taxes. OpenAI says it is not a fiduciary, registered investment adviser, broker-dealer, tax preparer or law firm. That removes one class of risk. A mistaken answer cannot directly drain an account through this feature. It does not remove the risk of persuasion. A confident suggestion about paying debt, moving cash or changing an investment can influence a person even when the system cannot press the final button. The conversational interface can make a recommendation feel personal because the answer knows balances, goals and obligations. The correct safeguard is not a paragraph that says informational purposes only. It is evidence inside the answer. For important decisions, the system should separate observed facts from calculations, assumptions and general guidance. It should show the date of each source, identify missing accounts, label estimated recurring charges and explain which financial memory changed the recommendation. It should also make uncertainty visible. If a debt payoff plan assumes a card's interest rate but Plaid did not supply the annual percentage rate, the answer should say so before presenting the plan. If a mortgage application question relies on a credit score that updates monthly, the age of that score belongs next to the answer. If an investment view excludes an unsupported retirement account, the tool should not quietly describe the remaining slice as the whole portfolio. Financial memory needs its own audit trail too. A memory can become stale even when it was correct when saved. Rent changes. A loan is repaid. A savings goal is completed. A household splits finances differently. A person changes jobs or moves to another state with different tax rules. The system should show when each memory was created, when it was last confirmed, which answers used it and whether it conflicts with connected data. Old memories should expire into a review state instead of remaining silently active forever. The distinction between memory and source data also needs to stay obvious. If I tell ChatGPT that my private loan balance is $4,000, that is user-supplied context, not a bank-verified fact. If I later pay it off but forget to update the memory, a good answer should ask for confirmation rather than carry the old obligation through every budget. Teams building similar products can borrow the useful pattern and avoid the easy mistake. Keep read access separate from action authority. Show the source and date for every material number. Preserve a clear system of record outside the model. Let users inspect and delete memories individually. Explain that disconnecting a source does not erase chats. Put deletion timelines in the main control surface, not only in help documentation. Test missing accounts, duplicate pending charges, stale credit files and conflicting memories before calling the experience personalized. For users, a short monthly check is enough to make the tool safer. Open the Accounts view and inspect connection status. Compare one dashboard total with the financial institution. Review financial memories and delete anything stale. Look through conversations that contain sensitive numbers before disconnecting a source. Check the training preference in Data Controls. Use temporary chat when you want a finance conversation that does not use connected accounts or create memory. The expansion to free plans will give many more people a useful way to understand messy financial records. Lowering the price of access matters, especially when paid financial advice and even decent budgeting software can feel out of reach. But a personal finance assistant earns trust by remembering the right things, forgetting them through predictable controls and showing its receipts. The bank drawer is open. Now every compartment needs a label, a date and an honest delete button.
01
WHAT ACTUALLY CHANGED
OpenAI announced on October 2 that Finances is rolling out to Free and Go users in the United States.
The product is available to eligible Free, Go, Plus and Pro users on the web, iOS and Android.
Users can connect financial accounts through Plaid and credit report data through Experian as separate sources.
The Finances dashboard can organize spending, bills, subscriptions, net worth, investments and credit information when enough connected data is available.
Users can ask questions in the Finances page or a regular conversation and receive answers grounded in connected financial context.
Financial memories can preserve user-supplied goals, obligations and household context across finance conversations.
Disconnected source data, conversation history and financial memories have separate management and deletion paths.
Temporary chats do not access connected financial accounts or use or create memories.
ChatGPT cannot move money, pay bills, make trades, change accounts or file taxes through Finances.
02
WHY THIS MATTERS
Free-plan access puts connected financial analysis in front of a much larger group of consumers.
A general-purpose assistant can combine transactions, credit data, questions and durable personal context in one interface.
Conversational explanations can make complex records more approachable than a conventional dashboard.
Separate data layers create separate responsibilities for inspection, correction, retention and deletion.
Incomplete institution feeds, delayed credit reporting and transaction categorization can make a plausible answer materially wrong.
Read-only access limits direct financial action but does not prevent bad advice from influencing a user.
Financial memories can improve relevance while also carrying stale goals or obligations into later decisions.
Visible sources, dates, assumptions and missing data are more useful safeguards than a generic disclaimer.
03
WHERE IT COULD HELP
- Review spending categories and ask which transactions produced a total.
- Find recurring bills or subscriptions that may deserve a closer look.
- Compare current spending with a recent period while checking source dates.
- Draft a budget or debt payoff scenario without giving the system authority to move money.
- Inspect portfolio allocation while confirming that every important account is connected.
- Discuss credit factors using the latest available Experian report and its update date.
- Store a savings goal as financial memory and periodically reconfirm that it remains current.
- Use temporary chat for questions that should not draw on connected accounts or create memory.
- Audit connected accounts, conversation history and financial memories as three separate data stores.
- Ask for sources, assumptions and missing fields before relying on a material conclusion.
KEEP A HAND ON THE WHEEL
OpenAI's documentation describes rollout, capabilities, controls and limitations, but the reviewed primary materials do not provide independent accuracy, privacy, security or consumer-outcome measurements. Availability may be gradual and remains limited to eligible users in the United States. Financial institutions can provide incomplete or delayed data, Experian credit information is not live activity, transaction categorization can be wrong and AI can make mistakes. Disconnecting a source does not delete existing conversation history. Synced Plaid data is deleted from OpenAI's systems within 30 days after removal, according to OpenAI. Finances is read-only and OpenAI says it is not a fiduciary or registered adviser. Watch for mandatory source receipts, memory aging, clearer deletion summaries, independent audits, complaint and correction metrics, and evidence that free users understand the difference between disconnecting an account and deleting a conversation or memory.
04
TERMS WORTH KEEPING
OPEN GLOSSARY CARD
Financial memory
A saved detail about a person's financial goals, obligations or circumstances that an assistant can reuse in later finance conversations.
OPEN GLOSSARY CARD
Data connector
A service that lets one product access selected information from another system under an authorized connection.
OPEN GLOSSARY CARD
Data freshness
How recently a record was updated and how closely it reflects the current real-world state.
SOURCES AND VERIFICATION STATUS
This article was written from the materials below. Product claims and dates were checked against those sources on October 3, 2026.
PUBLICATION RECEIPT: Reporting verified against OpenAI release notes and the current Finances documentation immediately before publication. Product capabilities and deletion timelines are attributed to OpenAI, and missing data, stale records, model error and adviser limitations remain explicit.
THE PUBLICATION ENGINE
WANT A SIGNAL OF YOUR OWN?
We build source-grounded publications, private briefings, and editorial systems for organizations with something useful to say.
WORK WITH US