THE SIGNAL IN ONE SENTENCE
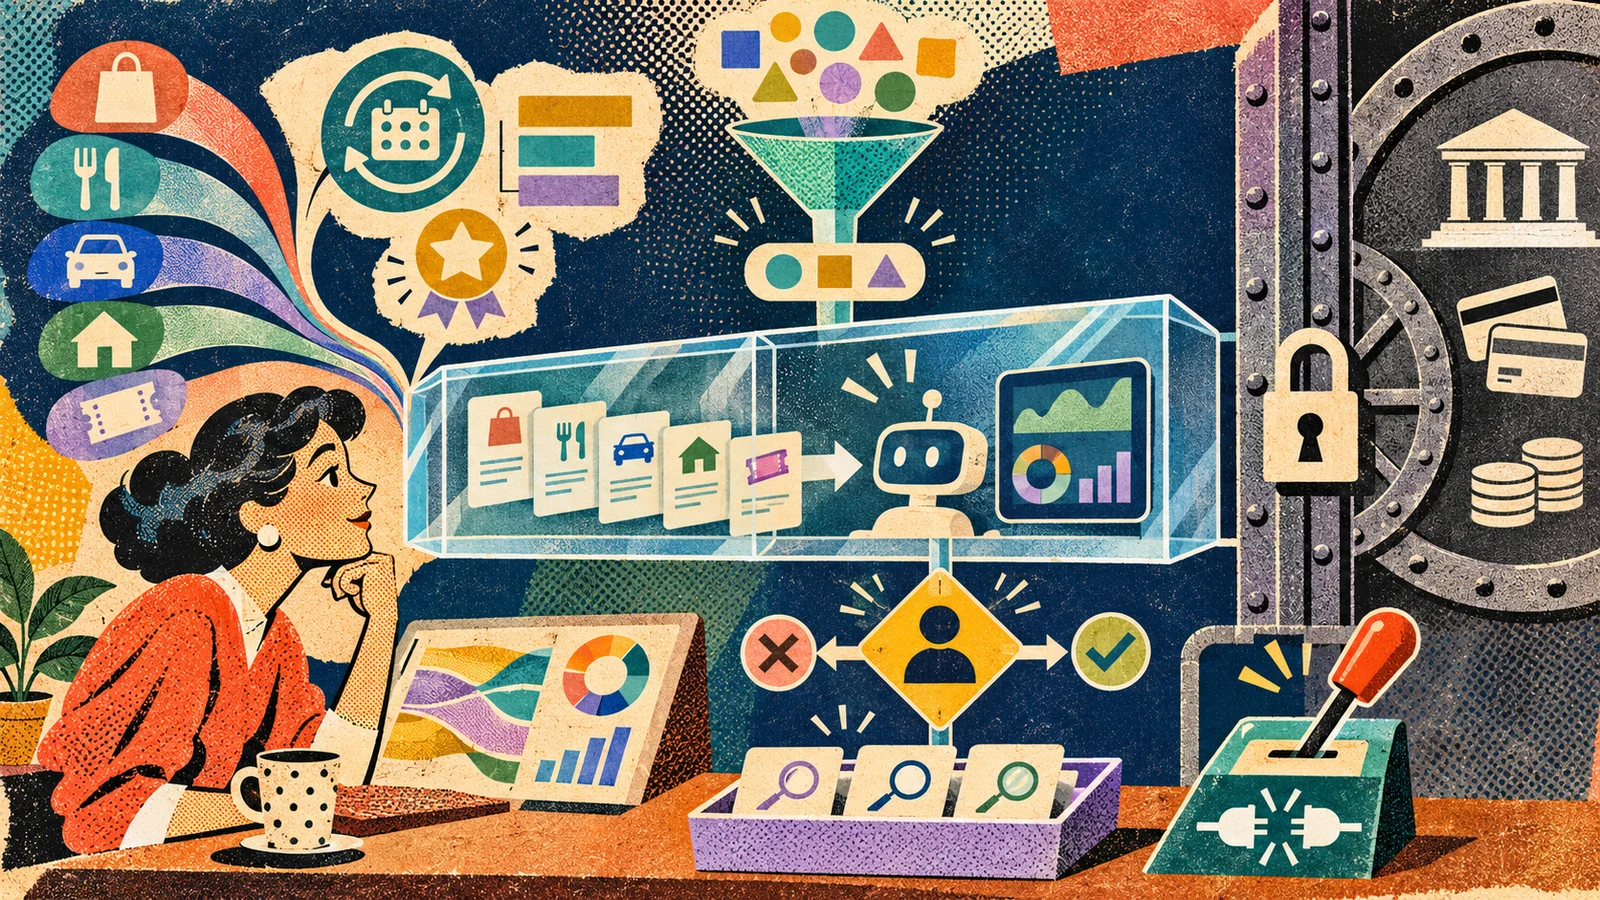
Gemini can now look at your spending. Google has added Google Wallet to the connected apps available through Personal Intelligence in Gemini. Eligible users in the United States can opt in, link financial accounts through services such as Plaid and ask questions about transactions, subscriptions, rewards, cash flow and budgets. The examples are appealingly ordinary. How much did I spend on groceries last month? Which subscriptions am I still paying for? Did any of them get more expensive? What did gifts and travel cost last year, and what would a sensible holiday budget look like this year? Google says Gemini can turn the answers into summaries and charts. It can use cards and passes in Wallet to summarize rewards and offers. The company also draws an important line: the connection is read-only. Gemini cannot use Wallet to make a transaction. It cannot update or delete a connected financial account. Google says it cannot move, manage or invest a user's money. Keep that line bright. Financial insight and financial authority are different products. One reads a ledger and suggests. The other can change the ledger. Combining them would turn a mistaken category, duplicated charge or misunderstood goal into an action with consequences. The plain signal is simple. Keep financial insight separate from financial authority. Read-only is safer than money-moving access. It is not low-stakes access. A transaction history is a remarkably detailed biography. It can reveal where someone sleeps, works, travels, worships, eats, seeks medical care and spends time. It can expose debt, donations, prescriptions, fertility care, legal bills, political interests, family relationships and periods of financial stress. The data do not need to include a bank balance to be sensitive. A merchant name, time and amount can say plenty. The connection should begin with an inventory. Before a person opts in, show exactly which Wallet records, bank accounts, credit cards and other linked financial accounts will be available. Name the account owner, institution, account type, date range and data fields. Distinguish the information held by Google Wallet from the information provided through Plaid. Do not replace that inventory with a cheerful switch marked personalized. Google's current eligibility rules also deserve to be visible before connection. The Wallet connected app is rolling out gradually. Google says a user must be at least 18, live in the United States, use a personal Google Account and have Keep Activity turned on. The feature is initially available only in English and works in the Gemini mobile and web apps, not in surfaces such as Gems or Gemini Live. Those are not footnotes. They shape the data bargain. Keep Activity is especially important. Google's help page says Gemini cannot connect to Google Wallet when that setting is off. Google's current privacy notice says information from Connected Apps is handled under the Gemini Apps privacy notice and can be used to provide and improve Gemini Apps. The privacy hub says that when Keep Activity is on, chats and shared material are saved in activity and can be used to provide, develop and improve services, including training generative AI models, with help from human reviewers. Google says the default auto-delete period is 18 months, which can be changed to 3 months, 36 months or indefinite. Google also says some reviewed chats and related data can be retained for up to three years, disconnected from the user's account. Deleting Gemini activity does not delete information stored by another Google service such as Wallet. That does not mean every transaction row will be reviewed or used for training. The public documents do not establish that. It means a user needs a precise explanation of what enters the chat, what is saved, which setting governs it and which deletion action affects which copy. Financial data should not arrive in a model context by surprise. Show a preview before the first query runs. For example: this request will read transactions from these three accounts, from October 1 through October 31, including merchant descriptors, dates, amounts, categories and pending status. Let the person narrow it. One account instead of all accounts. Thirty days instead of a year. Total by category instead of every transaction. Posted charges instead of pending ones. A subscription check instead of a full financial profile. That is data minimization with a user interface. Every answer should carry a data receipt. List the accounts used, the date range, the number of transactions, currencies, excluded records, missing periods, duplicates removed, transfers treated separately, pending charges included or excluded and the time the data were retrieved. If the answer says grocery spending increased, show which transactions were counted as groceries. If the answer identifies a subscription, show the recurring charges, merchant descriptor and interval that produced the conclusion. Merchant descriptors are messy. The name on a bank statement may be a parent company, payment processor, franchise operator or abbreviation. A restaurant can look like a hotel. A pharmacy can sell groceries. A marketplace transaction can hide the seller and product. One merchant can span several categories. Category labels are inferences, not facts carved into the card network. Make the inference visible. Let the user correct it. Preserve the correction for the current analysis without silently turning one person's preference into a universal rule. Transfers need special care. Moving money from checking to savings is not spending. Paying a credit-card bill should not count again after the underlying card purchases. A refund should reverse or offset a charge. A shared expense may only partly belong to the user. Cash withdrawals are not a reliable statement of what the cash bought. A budgeting assistant that misses those distinctions can confidently discover that the user spent the same dollar twice. Subscription detection also needs uncertainty. Regular charges can be rent, insurance, utilities, installment payments, donations or a club the user very much remembers. A price can change because of tax, usage, exchange rates or an annual renewal. The system can flag a likely recurring charge. It should not call it forgotten, wasteful or unwanted without asking. Show the evidence and the confidence. Offer a neutral review list. Keep cancellation outside the current connection unless the person deliberately enters a separate authorized workflow. Budgets are not discovered in transaction data. Past spending can help describe a pattern. It cannot decide what matters next. A person may spend more on travel because of a funeral, on food because relatives visited or on transport because a disability changed. A low expense can reflect deprivation rather than efficiency. A high expense can be the right choice. Gemini can draft a budget. The user must supply the goal, constraints and tradeoffs. Separate observation from recommendation. Observation: dining transactions totaled this amount over this period under these category rules. Inference: several charges appear to recur monthly. Suggestion: reducing one category could move the user toward a stated savings goal. Decision: the person chooses whether the suggestion fits their life. Do not blend all four into a single sentence that sounds like financial advice. Google's privacy hub says not to rely on Gemini for financial or other professional help. That warning belongs near consequential suggestions, not three links away. High-stakes questions should slow the system down. Debt repayment, retirement, taxes, investments, insurance, benefits and decisions involving a vulnerable household member may require current law, contractual terms or a qualified professional. A spending summary can organize facts. It cannot certify the right decision. The model should state what it does not know. It may not see cash, accounts that were not linked, a partner's finances, future income, debts outside the connection, pending disputes or an upcoming expense. A partial picture should not introduce itself as the user's finances. Read-only must remain technically enforced. The model should not receive payment credentials. It should not have a hidden route to transaction APIs. The Wallet connector should expose only the data needed for supported read operations. A prompt cannot upgrade permission. Any future move from insight to action should require a separate product boundary, a separate permission and a fresh human approval for the exact transaction. Do not let the convenience of one connected-app setting become standing authority over money. Access controls need household reality. A phone, tablet or browser may be shared. A family member may have access to a device but not to the account owner's financial history. Notifications, chat titles, suggested prompts and recent conversations can reveal sensitive information even when the source account remains protected. Use device authentication for sensitive views. Hide financial details from lock-screen previews. Make session and account identity obvious. Support a quick way to clear the visible conversation without pretending that clearing the screen deletes every stored copy. Disconnection should be legible. Google says users can disconnect Wallet from Gemini at any time and can unlink financial accounts in Wallet settings. Those are different controls. Show what each one does. Disconnecting Gemini should stop new reads. Unlinking a financial account should stop Wallet from receiving new data from that connection. Deleting a Gemini chat should address the chat copy. Deleting or correcting source data belongs to the service that holds it. One action may not clean up the others. Give users a deletion map with links, status and expected timing. Do not use the word delete when the action only hides or disconnects. Corrections need a home too. If Gemini misclassifies a merchant or duplicates a charge, the user should be able to correct the analysis without changing the bank's source record. If the source record itself is wrong, direct the user to the institution or Wallet connection that can address it. Keep source corrections, analysis corrections and preference changes separate. The feature should be evaluated on more than whether people enjoy a colorful chart. Measure transaction coverage, category accuracy, duplicate detection, transfer handling, refund handling, subscription precision, currency conversion, missing-data disclosure, correction rate and the share of recommendations that users reject after seeing the evidence. Test across banks, card types, merchant descriptors, languages, household structures, income volatility and accessibility needs. Measure whether people understand that the connection is read-only and whether they can disconnect it. Track privacy outcomes: unexpected data exposure, wrong-account access, sensitive text in notifications, deletion confusion and support resolution. Publish the limits. Google's November 13 announcement establishes the intended uses and read-only boundary. The help pages establish current eligibility, surfaces and settings. They do not publish independent accuracy, budgeting outcomes, privacy audits or subgroup evaluations for the Wallet connection. That is normal for a new feature. It is also why the interface needs to show its work. Financial context can make an assistant genuinely more useful. It can also make a mistake feel personal and a suggestion feel authoritative. Keep the sequence honest. The user chooses the accounts and time range. The connector reads only the necessary records. The system shows the receipt. The model separates facts from inferences and suggestions. The person corrects the categories, supplies the goal and makes the decision. The money stays outside the model's authority. That is not a missing feature. It is the feature that makes the rest worth trying.
01
WHAT ACTUALLY CHANGED
Google added Google Wallet as a connected app for Personal Intelligence in Gemini, with a gradual rollout to eligible users in the United States.
Users can opt in and ask Gemini for information and personalized insights based on data available through Google Wallet.
Users may link financial accounts through services such as Plaid so Wallet can provide transaction context for deeper analysis.
Google's examples include spending summaries, cash-flow charts, subscription checks, price-change flags, rewards summaries and tailored budget suggestions.
Google says the connection is read-only and cannot move, manage or invest money.
The Wallet connected app cannot make transactions or update or delete connected financial accounts.
Current eligibility requires a user to be at least 18, live in the United States, use a personal Google Account and have Keep Activity turned on.
The feature is initially English-only and available in Gemini mobile and web apps, but not in certain surfaces such as Gems or Gemini Live.
Users can disconnect Wallet from Gemini and separately unlink financial accounts through Wallet settings.
02
WHY THIS MATTERS
A transaction history can reveal sensitive details about health, location, relationships, beliefs and financial stress.
Read-only access reduces transaction risk but still creates privacy, retention, classification and advice risks.
Merchant descriptors, categories, transfers, refunds and recurring charges can be incomplete or misleading.
A polished chart can hide missing accounts, duplicate transactions, pending charges or uncertain classifications.
Past spending describes behavior but cannot determine a person's goals, obligations or future priorities.
Google requires Keep Activity for the Wallet connection, so users need clear information about storage, review and deletion controls before opting in.
Separating facts, inferences, suggestions and decisions keeps a budgeting assistant from sounding like an authorized financial adviser.
The technical boundary preventing money movement should remain separate from any future transaction capability.
03
WHERE IT COULD HELP
- Show the accounts, owners, date ranges and fields that will be available before connection.
- Let users limit a request to selected accounts, shorter periods and summarized fields.
- Attach a receipt listing accounts, transaction counts, currencies, exclusions, missing periods and retrieval time.
- Show which transactions support every category total, subscription flag or price-change claim.
- Mark merchant categories as inferences and let users correct them.
- Separate transfers, card payments, refunds, cash withdrawals and shared expenses from ordinary spending.
- Label recurring charges as likely subscriptions until the user confirms them.
- Separate observations, inferences, suggestions and final decisions in the interface.
- State missing accounts, cash activity, debts, income and future obligations before offering a budget suggestion.
- Keep payment credentials and transaction APIs outside the read-only connector.
- Require a separate permission and fresh human approval for any future money-moving action.
- Protect sensitive financial views on shared devices and in notifications.
- Provide a deletion map for Gemini chats, Gemini activity, Wallet connections and source accounts.
- Distinguish corrections to source records from corrections to the model's analysis.
- Measure category, duplicate, transfer, refund and subscription accuracy alongside correction and rejection rates.
- Publish privacy, accessibility, subgroup and financial-outcome evaluations before making broad benefit claims.
KEEP A HAND ON THE WHEEL
Google's November 13 announcement and current Gemini help pages document the feature, eligibility rules, supported surfaces and read-only boundary. They do not provide independent measures of transaction coverage, category accuracy, subscription detection, budgeting outcomes, privacy, security or subgroup performance. Google says the Wallet connected app is rolling out gradually, so an otherwise eligible user may not see it immediately. The current feature requires users to be at least 18, live in the United States, use a personal Google Account and keep Keep Activity on. It is initially English-only and unavailable in some Gemini surfaces. Google says Gemini can read information from connected accounts but cannot move, manage or invest money. The help page also says the Wallet connected app cannot make transactions or update or delete connected financial accounts. Google's general Gemini Apps privacy notice says information from Connected Apps is handled under that notice. Keep Activity, human review, retention and deletion behavior can depend on settings and the service holding each copy. The public documents do not establish that every Wallet transaction is used for training or reviewed by a person. Google's privacy hub warns users not to rely on Gemini for financial or other professional help. The data receipt, account scoping, classification controls, deletion map, separation of facts from suggestions and evaluation metrics in this article are Plain Signal analysis. Official announcement date: November 13, 2026. Verified November 14, 2026.
04
TERMS WORTH KEEPING
OPEN GLOSSARY CARD
Human control
The practical ability and authority of people to understand, direct, interrupt or stop an automated process before unacceptable harm occurs.
OPEN GLOSSARY CARD
Non-binding advice
A recommendation that an organization should consider but is not legally required to follow.
OPEN GLOSSARY CARD
View-only access
Permission to inspect something without changing, deleting, or publishing it.
SOURCES AND VERIFICATION STATUS
This article was written from the materials below. Product claims and dates were checked against those sources on November 14, 2026.
THE PUBLICATION ENGINE
WANT A SIGNAL OF YOUR OWN?
We build source-grounded publications, private briefings, and editorial systems for organizations with something useful to say.
WORK WITH US