THE SIGNAL IN ONE SENTENCE
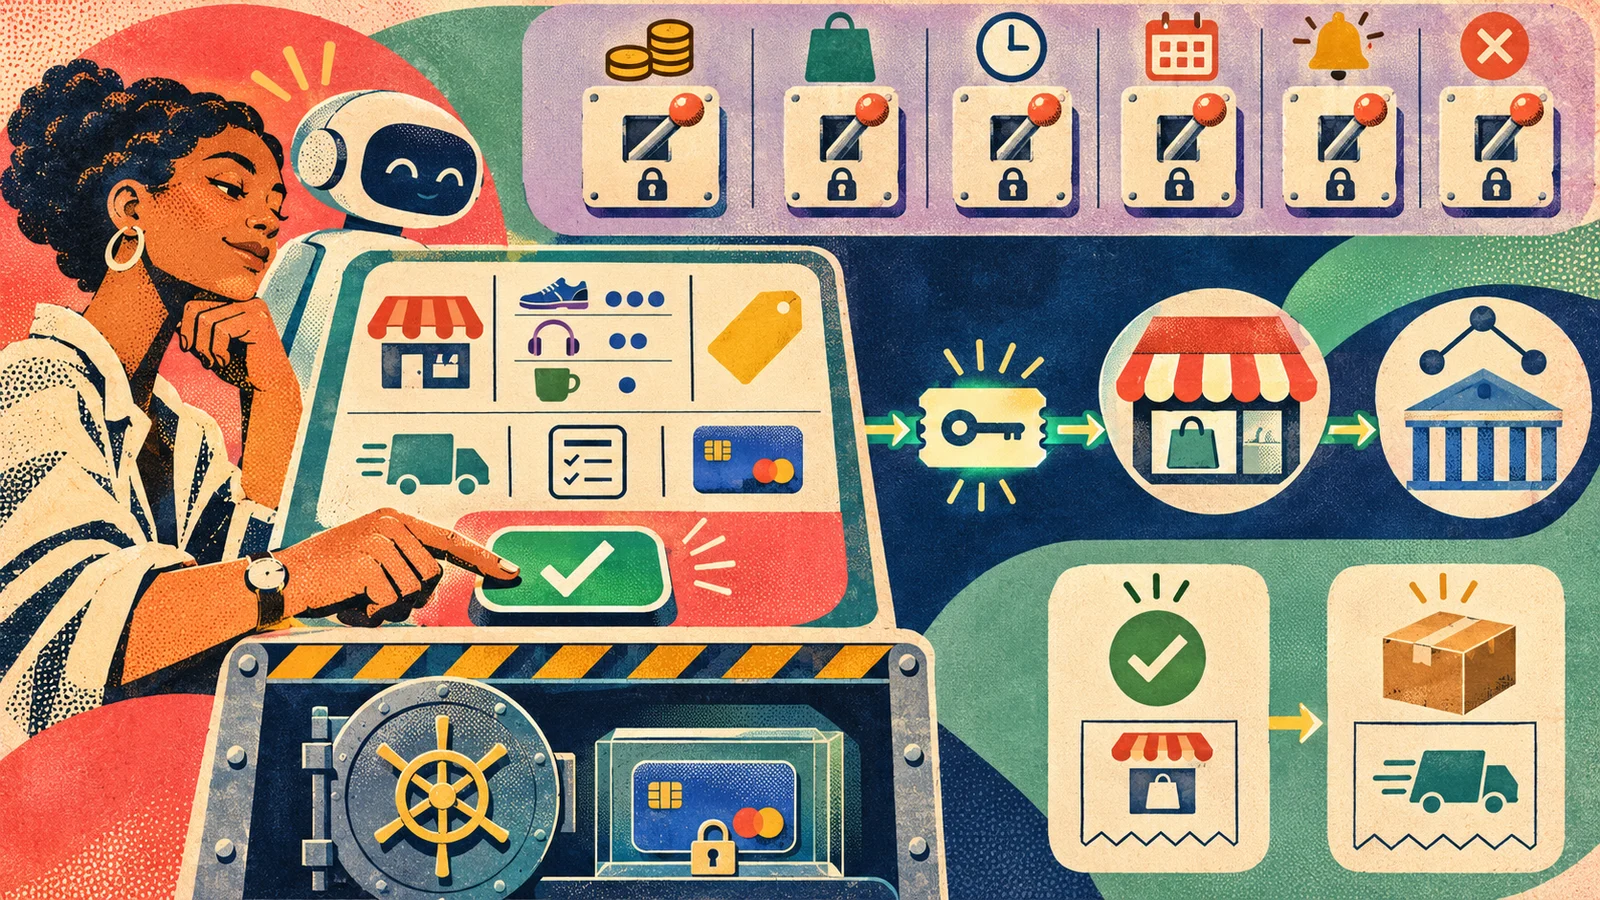
OpenAI has given its shopping agents a wallet. That sentence sounds more autonomous than the current product actually is, which is good. ChatGPT Wallet is rolling out first through dots, OpenAI's agent experiences, to eligible ChatGPT Pro subscribers who are at least 18 and live in the United States. A user can add an eligible credit or debit card, ask the agent to help shop and let it reach a checkout. Then the agent has to stop. The user reviews the merchant, items, total and selected card. The purchase proceeds only after a fresh security check, such as Face ID or a fingerprint. OpenAI says the underlying payment network supplies a substitute payment credential, so the agent and business do not receive the person's actual card details. The user's card can still earn its usual rewards and keep eligible dispute protections. The merchant remains responsible for the order, delivery, returns and refunds. OpenAI also says the approval does not itself mean the merchant accepted the order. Websites may block agent purchases or fail during the process. Those details make the current boundary clear. The agent can research, compare and prepare. A person approves one specific transaction. The merchant confirms it. The delivery system fulfills it. Each step needs its own receipt. Do not blur those steps into one cheerful animation. The plain signal is simple. Keep every purchase behind a fresh human check. A useful approval screen should begin with the legal merchant, not merely the storefront name. Marketplaces, payment facilitators and third-party sellers can make the counterparty unclear. Show who will charge the card, who will ship the item and who will handle the return. Then show the exact goods. That means product, variant, size, color, quantity, condition, seller and any permitted substitution. A tiny product picture is not enough. If the agent researched one laptop and the cart contains a similar model with less memory, the difference belongs in the approval screen. Show the full price. The total should include item price, tax, shipping, service fees, tips, discounts, currency and any amount that may change. If a merchant will calculate tax later, say that plainly. If the price moved since the agent recommended the item, show the old and new values. Show time. A user needs the delivery estimate, cancellation deadline, return window and subscription interval. A free trial that becomes a monthly charge is not a one-time purchase. An automatic reorder is not a bag of coffee. Recurrence deserves a separate, unmistakable approval. Show the selected card and the consequences of changing it. Different cards can carry different rewards, foreign-transaction fees, warranty coverage and dispute protections. The interface should not silently choose the card that is easiest for the agent or payment provider. Only after those facts are visible should the user perform the security check. The check must bind the person to the transaction that was displayed. It should not create a floating permission that the agent can reuse after a price, quantity, seller, delivery address or term changes. If anything material changes, ask again. That rule sounds fussy until you imagine the alternatives. An item goes out of stock and a merchant substitutes another. A discount expires between review and authorization. A marketplace switches sellers. A tip is added. Shipping changes from free to overnight. A one-time order becomes a subscription. The agent retries after a timeout and the merchant processes both requests. Every one of those cases can produce a transaction the user did not actually approve. The approval record should be durable. Preserve the merchant identity, item details, quantity, total, currency, tax, shipping, fees, discount, recurrence, delivery address, refund terms, selected card, timestamp, approval method, substitute payment credential identifier, merchant authorization response and final order confirmation. Do not store a biometric template in the shopping record. Record that the device completed the required check, using the minimum evidence needed to prove the gate occurred. The payment credential is safer than sharing the card number, but it is not magic dust. The token needs narrow scope. Bind it to the merchant, amount, currency, time window and transaction where the payment network supports those limits. Expire it quickly. Prevent its use for a different seller or a larger amount. Keep it out of prompts, screenshots, analytics logs and support transcripts. The agent should never receive more payment material than it needs. Retries need an idempotency key, which is a stable identifier that tells the merchant and payment system that two requests represent one intended purchase. A timeout should not create a second order. A user tapping approve twice should not create a second charge. A resumed agent session should not start over with a fresh identity. The system also needs a state machine that admits uncertainty. A payment can be approved by the user but declined by the issuer. It can be authorized by the issuer but rejected by the merchant. The merchant can accept the payment but fail to return an order number. A confirmation page can disappear while the order still exists. The agent should say which state it can prove. User approved is not the same as card authorized. Card authorized is not the same as order confirmed. Order confirmed is not the same as shipped. Shipped is not the same as delivered. When the state is uncertain, the agent should check the merchant account, email receipt or payment record before trying again. It should not hammer the buy button with the confidence of a woodpecker who just discovered venture capital. Fraud systems will sometimes block legitimate agent purchases. An unfamiliar device, automated browsing pattern, new merchant, unusual amount or changed delivery address can trigger a review. That does not mean the agent should route around the safeguard. It should explain the decline in the limited terms available, offer a human route and avoid repeated attempts that make the pattern look worse. Merchants need an agent-aware confirmation path. The receipt should say that an agent prepared the purchase and a person approved it. It should include the merchant order number, exact items, final total, delivery details and return path. The merchant should be able to distinguish an abandoned cart from a confirmed order without relying on the agent's memory. Returns remain human business. The user may need to contact a seller, print a label, schedule a pickup, explain damage or dispute a charge. The agent can help organize the evidence, but it should not hide the merchant's terms or promise that a refund is guaranteed. Preserve the product page, approval record, order confirmation, shipping record, messages, return request, merchant response and payment status. Give the user a portable transaction packet that can be shared with the merchant, issuer or dispute team. Accessibility is part of the gate. A biometric check needs a secure fallback for people who cannot use it. The approval screen needs screen-reader labels, keyboard operation, adequate contrast, predictable focus, plain language and enough time to review. Important differences cannot rely only on color or a tiny animation. A user with low vision should be able to hear the merchant, items, quantity, total and recurrence before approving. A person with limited dexterity should not need a precision gesture. A shared device should not reveal purchase history to the wrong household member. The initial age limit also matters. OpenAI says the rollout is for adults 18 and older. The system should enforce that boundary rather than infer age from shopping behavior. Family accounts, authorized users and shared cards create additional questions about who may approve and who receives alerts. Privacy extends beyond payment credentials. A shopping request can reveal health conditions, religion, sexuality, political interests, pregnancy, financial stress, location and household relationships. Delivery addresses and purchase histories can be more revealing than a card number. Minimize what enters the agent context. Separate shopping history from general conversation memory. Let users delete saved cards and disconnect the wallet. Explain which party stores the request, cart, payment token, receipt and support logs, and for how long. Do not train a general model on a person's sensitive purchase details without a clear, lawful and meaningful choice. The future version deserves more scrutiny than the current one. OpenAI says it expects that users may eventually delegate purchases more fully by setting limits and preferences. That is an aspiration, not a reason to weaken the present approval gate. Standing delegation should be narrow enough to read in one breath. For example: this merchant, this product category, no more than this amount per purchase and this amount per month, only to this address, only until this date, no subscriptions, no substitutions, no controlled or high-risk goods, and alert me before anything outside the ordinary pattern. The permission should expire. The user should be able to pause or revoke it immediately. Every attempted transaction should generate a receipt, including blocked and failed attempts. Exceptions should return to a human. A higher price, new seller, changed quantity, different delivery address, recurring charge, unusual shipping fee, age-restricted item or weak merchant identity should stop the agent. Delegation is not a license to improvise around the limit. Do not make the user hunt through settings to learn what the agent may buy. Put active permissions in one place. Show remaining budgets, recent attempts, upcoming recurring charges and the exact rule used for each decision. Let the user simulate what a permission would allow before turning it on. The system should publish outcomes, not only convenience stories. Report purchase completion, user cancellations, issuer declines, merchant failures, duplicate orders, incorrect items, changed totals, unauthorized attempts, returns, refunds, disputes, false fraud blocks, human interventions, accessibility failures and time to resolution. Separate attempted, approved, authorized, confirmed, shipped, delivered, returned and disputed transactions. Measure how often the approval screen catches a changed seller, price or term. Measure whether users understand that approval is not merchant confirmation. Test whether people can revoke a permission during an incident. Test whether the system can recover without a duplicate charge after a network failure. Publish results by merchant type, transaction size and device class where privacy allows. Commission independent security and usability testing before widening the rollout or adding standing delegation. ChatGPT Wallet is a meaningful change because it connects an agent's recommendation to a real financial action. The substitute payment credential reduces one familiar exposure. It does not decide whether the purchase is right, whether the seller is trustworthy, whether the total changed, whether a retry will duplicate the order or whether the user understood the terms. That work belongs in the transaction boundary. Keep the sequence visible. The user asks. The agent researches. The agent assembles a cart. The user reviews the exact transaction. A fresh security check approves that transaction. The payment network issues a scoped credential. The merchant confirms the order. The system tracks fulfillment. The receipt survives long enough to support a return or dispute. That is not friction to eliminate. It is the part that turns an agent with a wallet into a tool a person can still control.
01
WHAT ACTUALLY CHANGED
OpenAI introduced ChatGPT Wallet for agent-assisted purchases through dots, with an initial rollout to eligible ChatGPT Pro subscribers aged 18 and older in the United States.
Users can add an eligible credit or debit card and select it during an agent purchase flow.
Before a purchase proceeds, the user reviews the merchant, items, total and selected card, then completes a fresh security check such as Face ID or a fingerprint.
OpenAI says participating payment networks provide substitute payment credentials, so the agent and business do not receive the user's actual card details.
The user's card can retain its normal rewards and eligible dispute protections.
The merchant remains responsible for the order, delivery, returns and refunds.
OpenAI says some websites may not support agent purchases and that user approval does not itself confirm that the merchant accepted the order.
OpenAI describes more complete future purchasing delegation with user-set limits and preferences, but that is not the current general flow.
02
WHY THIS MATTERS
A shopping agent crosses from advice into a consequential financial action when it can prepare and transmit a purchase.
Hiding the real card number reduces exposure but does not prevent a changed seller, wrong item, duplicate order or misunderstood subscription.
A fresh approval can bind one person to one visible transaction and make material changes trigger a new decision.
Approval, issuer authorization, merchant confirmation, shipment and delivery are different states that need separate evidence.
Retries after timeouts can create duplicate orders unless merchants and payment systems use stable transaction identifiers.
Purchase requests and delivery data can reveal sensitive information even when payment credentials remain protected.
Future standing delegation could remove the most useful current safeguard unless permissions are narrow, expiring and easy to revoke.
Independent outcome reporting is needed before convenience claims can establish reliability or consumer benefit.
03
WHERE IT COULD HELP
- Show the legal merchant, seller, shipper and return owner before approval.
- Display exact items, variants, quantities, condition, substitutions and every material change since research.
- Show the complete total, currency, tax, shipping, fees, discounts, tips and recurring terms.
- Require a fresh approval whenever the seller, item, quantity, total, address, delivery or term changes.
- Bind substitute payment credentials to the narrowest available merchant, amount, currency and time scope.
- Use idempotency keys and merchant-side uniqueness checks to prevent retries from creating duplicate orders.
- Separate user approval, issuer authorization, merchant confirmation, shipment, delivery, return and dispute states.
- Preserve a portable transaction packet with the approval, order, shipping, return and payment evidence.
- Provide secure non-biometric approval fallbacks and accessible review interfaces.
- Minimize purchase history, delivery data, payment tokens and support logs across agent memory and analytics systems.
- Make future delegation permissions merchant-specific, category-specific, amount-limited, expiring and instantly revocable.
- Send alerts for blocked, failed and completed delegated attempts, not only successful charges.
- Return any price, seller, quantity, address, recurrence or risk exception to a person.
- Publish completion, cancellation, decline, duplicate, incorrect-item, return, refund, dispute and accessibility outcomes.
KEEP A HAND ON THE WHEEL
OpenAI's November 13 announcement documents the product design and initial availability. It does not establish broad merchant compatibility, transaction success, fraud reduction, consumer savings, return performance or dispute outcomes. The rollout is limited to eligible ChatGPT Pro subscribers aged 18 and older in the United States. Card and merchant eligibility can vary. OpenAI says payment networks create substitute payment credentials so the agent and business do not receive the user's actual card details. The announcement does not publish the precise scope, lifetime or reuse controls for every network credential. OpenAI says users review the merchant, items, total and selected card and approve with a security check. It also says approval does not itself confirm the order. The merchant remains responsible for fulfillment, returns and refunds. OpenAI says some websites may not support purchases made through ChatGPT agents. The company describes fuller delegation with user-set preferences and spending limits as a future expectation. It is not evidence that broad standing delegation is currently available or safe. The transaction receipt, material-change rule, state machine, token-scoping recommendations, idempotency design, accessibility requirements, delegation template and outcome metrics in this article are Plain Signal analysis. Official announcement date: November 13, 2026. Verified November 14, 2026.
04
TERMS WORTH KEEPING
SOURCES AND VERIFICATION STATUS
This article was written from the materials below. Product claims and dates were checked against those sources on November 14, 2026.
THE PUBLICATION ENGINE
WANT A SIGNAL OF YOUR OWN?
We build source-grounded publications, private briefings, and editorial systems for organizations with something useful to say.
WORK WITH US